Author: bizdoctr_owner

  • Smart Car Finance and Payment Strategies for Businesses

    Smart Car Finance and Payment Strategies for Businesses

    Vehicles can be central to day-to-day business operations. A company may use cars or vans to transport employees between sites, carry tools and equipment, visit clients, or provide services at customer locations. For retailers, wholesalers, and other organisations, vehicles can also support deliveries and the movement of stock. The right vehicle can help staff work efficiently, maintain reliable service, and reach customers or locations that would otherwise be difficult to access. Because business needs change, choosing how to acquire vehicles is an important operational and financial decision.

    Many businesses finance a vehicle rather than pay its full purchase price upfront to preserve working capital. Keeping more cash available can help cover wages, inventory, rent, repairs, and unexpected costs, or fund opportunities that support growth. Financing also spreads the cost into regular payments over an agreed period, which can make expenditure easier to plan and budget for. Instead of committing a large sum at once, a business can retain funds for other priorities while still obtaining a vehicle needed for its work. Depending on the agreement, payment structures may also offer predictability, although interest and fees affect the total amount paid.

    Spreading payments may help align vehicle expenses with the period in which the vehicle is being used to generate value. This can be relevant for businesses that depend on transport to complete contracts, make deliveries, or serve customers. However, financing is not automatically the most suitable choice. The decision should reflect cash flow, how frequently and intensively the vehicle will be used, expected ownership or replacement plans, and the business’s legal and tax structure. It is also important to compare the deposit, payment schedule, interest rate, fees, mileage or usage limits, and any end-of-term obligations. Reviewing these factors together can help a business choose an arrangement that supports operations without placing unnecessary pressure on its finances.

    Businesses can fund a vehicle through hire purchase, a business loan, leasing, or an outright cash purchase. The right choice depends on cash flow, expected mileage, how long the vehicle will be needed, and whether eventual ownership matters. Comparing the full cost over the agreement—not only the monthly payment—helps reveal the practical differences.

    With hire purchase or installment finance, the business typically pays a deposit followed by fixed payments over an agreed term. The finance provider generally retains legal ownership until the final payment, after which the business can own the vehicle, subject to the agreement’s terms. This route can spread the purchase cost while supporting eventual ownership, but interest, fees, and the deposit increase the total amount paid. A business loan also spreads costs, but the business usually buys and owns the vehicle from the outset; repayments cover the borrowing, and the vehicle may serve as security depending on the loan.

    Leasing gives the business use of a vehicle for a defined period in return for regular payments, often with mileage and condition requirements. Under a finance lease, the business generally does not automatically gain ownership at the end. It may have obligations such as making a final payment or arranging a sale, depending on the contract. Some other arrangements, including hire purchase or certain lease products with a purchase option, may allow the business to acquire the vehicle, but the option and its cost must be confirmed in writing. Leasing can preserve cash and provide predictable costs, although excess mileage, damage, or early termination may incur charges.

    A cash purchase avoids interest and ongoing finance commitments, and gives the business ownership immediately. However, it ties up capital that could be used elsewhere and leaves the business responsible for resale value and depreciation. Before deciding, compare deposits, interest rates, fees, contract length, mileage limits, end-of-term obligations, and early-termination conditions. Check whether maintenance, taxes, or other services are included, and assess affordability under realistic cash-flow assumptions. A lower monthly payment may still mean a higher overall cost or more restrictive terms.

    Estimate the full cost of using a business vehicle before choosing a finance plan. Include regular loan or lease payments, insurance, fuel or charging, routine maintenance, repairs, registration, taxes, and any required fees. Account for less frequent expenses such as tyres, parking, tolls, and replacement transport if the vehicle is unavailable. Convert annual or occasional bills into monthly amounts to make comparisons easier, and base usage costs on realistic mileage and current supplier estimates. Separate fixed costs from those that vary with distance, vehicle condition, or energy prices.

    Test affordability against several revenue scenarios rather than relying only on an expected month. Model a normal trading period, a slower period, and a temporary disruption, then check whether the business can still meet vehicle payments alongside payroll, tax, and other essential commitments. Consider the timing of customer receipts as well as total income: a payment may be affordable on paper but difficult to manage if it falls due before revenue arrives. Where possible, align payment dates with reliable cash inflows, and compare monthly, quarterly, or other available schedules for their effect on both cash flow and total cost.

    Build a reserve for irregular expenses, including major repairs, insurance renewals, excess mileage charges, and periods of downtime. The appropriate amount will depend on the vehicle’s age, usage, warranty, and the business’s ability to absorb unexpected bills; review it as those factors change. Before signing, read the finance contract carefully. Check whether the interest rate can vary, whether a balloon or residual payment is due at the end, and what late fees apply. Confirm any mileage limits, early-settlement terms, and conditions for changing payment dates or schedules. Payment flexibility can help during a temporary cash-flow shortfall, but do not assume it is automatic: understand the process, costs, and eligibility requirements in advance. Revisit the full cost estimate regularly, comparing actual spending with forecasts so that budgets and reserves remain realistic.

    The advertised monthly payment is only one part of a business vehicle’s true cost. Tax treatment and accounting requirements can change the amount a business ultimately pays, the timing of deductions, and how the vehicle appears in its financial statements. These rules differ by jurisdiction and may also depend on the vehicle type, business structure, financing arrangement, and proportion of personal use. A vehicle used partly for private travel may receive different treatment from one reserved exclusively for business.

    Before signing, ask a qualified accountant to confirm whether finance interest or lease payments are deductible, and whether any deduction is limited by vehicle value, emissions, or business-use share. Clarify how depreciation or local capital allowances apply, including the timing and limits of any claim. Sales tax or value-added tax may be recoverable only in certain circumstances, and private use can affect the amount claimed. The accounting treatment of a purchase, loan, or lease can also differ, so compare the options using the relevant rules rather than assuming that a lower payment creates a lower overall cost.

    Reliable records support both compliance and sound budgeting. Ask what evidence is required for business mileage, fuel, charging, maintenance, and any personal use. A mileage log should be kept consistently and include the details required locally; retain contracts, invoices, payment records, and expense receipts as well. Confirm how the business should report the vehicle and associated costs, and whether employees or owners face separate tax consequences when they use it privately.

    Use a practical checklist before committing: define the vehicle’s business purpose and expected annual use; compare total contract costs, including fees, insurance assumptions, servicing, and any final payment; confirm affordability under realistic cash-flow conditions; and review end-of-term mileage limits, return standards, purchase options, and early-exit charges. Consider whether the vehicle will still suit future fleet needs as workloads or staffing change. Finally, obtain professional advice based on the business’s location and circumstances, and keep written estimates of the tax treatment alongside the finance quotes. This helps decision-makers assess both operational fit and the likely after-tax cost.
  • Smarter Workflows: Using AI and Technology to Improve Business Productivity

    Smarter Workflows: Using AI and Technology to Improve Business Productivity

    Smarter Workflows: Using AI and Technology to Improve Business Productivity

    Make technology serve the work

    Technology can help a business get more done, but its value depends on how well it addresses real needs. Start by identifying tasks that consume time without requiring much judgment, such as sorting routine requests, preparing recurring reports, or scheduling appointments. Digital tools can streamline these activities and give employees more time for customer service, planning, and creative problem-solving.

    Artificial intelligence can extend these benefits. Depending on the task, AI tools may summarize documents, draft communications, categorize inquiries, or highlight patterns in business data. Treat these capabilities as support for people rather than automatic replacements for their expertise. Employees should review important outputs, especially when accuracy, context, or customer trust is at stake.

    Choose tools with a clear purpose

    Before adopting a new system, define the problem it is meant to solve and how success will be measured. Useful indicators might include time saved, fewer errors, faster response times, or improved employee experience. Compare those results with the cost of the tool, including setup, training, maintenance, and the time needed to manage it.

    Begin with a limited trial instead of changing several processes at once. Select a task with manageable risks, involve the people who perform it, and gather feedback throughout the test. A small, well-supported improvement can reveal what works and where adjustments are needed before a broader rollout.

    Protect quality, privacy, and trust

    Productivity gains should not come at the expense of data security or sound decisions. Review how a tool stores and uses information, restrict access appropriately, and avoid entering sensitive business or customer details into systems that have not been approved for that purpose. Establish clear guidelines for reviewing AI-generated content and correcting errors.

    Training matters, too. Employees need practical instruction on when to use a tool, how to check its results, and when human judgment must take priority. Invite questions and share examples of effective use so teams can build confidence without overstating what technology can do.

    Improve continuously

    Business needs change, and tools that once helped may become inefficient or unnecessary. Revisit results regularly, ask employees what creates friction, and refine workflows based on evidence. A thoughtful combination of technology, AI, and human expertise can make everyday operations more efficient while preserving the care and accountability that customers expect.

  • Preparing for Disruption: A Resilience Plan for Businesses, Banking, and Networks

    Preparing for Disruption: A Resilience Plan for Businesses, Banking, and Networks

    Preparing for Disruption: A Resilience Plan for Businesses, Banking, and Networks

    A useful resilience plan begins with a clear map of setbacks that could interrupt essential work. Review three connected areas: business operations, banking and cash flow, and digital or professional networks. Operational risks may include a supplier failing, demand falling suddenly, or too few employees being available to deliver products and services. Financial risks can include restricted access to funds, payment-processing outages, fraud, or the loss of a key banking relationship. Network risks extend beyond technology: an internet or telecommunications failure, cyber incident, or the loss of a critical partner or contact may also prevent routine activities.

    Assess each risk consistently by considering its likelihood, potential impact, early warning signs, and speed of onset. A supplier’s deteriorating delivery record may provide advance notice, while a cyber incident or payment outage could disrupt operations with little warning. Estimate which services would be affected, how many customers or employees could be impacted, and how long the organization could operate without the resource. Identify whether alternatives exist, such as another supplier, a backup payment method, or a secondary communications channel. Consider dependencies between risks: a network outage might prevent access to banking services, while a staff shortage could delay the response to fraud or a technology failure.

    Involve leaders alongside employees who understand day-to-day processes. Senior decision-makers can explain strategic priorities and acceptable levels of disruption; frontline staff can identify practical dependencies, workarounds, and warning signs that may not appear in formal records. Document the people, systems, facilities, suppliers, accounts, and contacts each essential service relies on, including who can authorize access or action. Then distinguish ordinary problems, which existing procedures can manage, from events that could threaten continuity, safety, or financial stability. This shared assessment helps the organization prioritize preparation around credible, consequential setbacks rather than treating every inconvenience as a crisis.

    Financial resilience begins with a clear picture of when money enters and leaves the business. Build a rolling cash-flow forecast covering at least the next several months, updating it regularly with realistic sales assumptions, payment delays, payroll, taxes, debt service, and seasonal costs. Model a downside case, such as a major customer paying late or revenue falling, so leaders can see when a shortfall may arise and respond early. Compare actual results with the forecast and investigate variances rather than treating projections as fixed.

    Set an emergency reserve based on the company’s exposure, fixed commitments, access to credit, and the time needed to restore normal operations. There is no universal target; determine a practical amount through scenario testing and review it as the business changes. Monitor receivables closely, invoice promptly, follow up on overdue balances, and understand customer concentration. Review expenses and debt obligations regularly, checking maturities, interest rates, covenants, and refinancing needs. Identify costs that can be reduced without weakening essential staffing, security, service quality, or revenue-generating capacity. Agree in advance who can approve spending changes and which actions require escalation.

    Prepare for banking and payment interruptions by documenting how to contact the bank, which support channels operate outside business hours, and how urgent cases are escalated. Confirm account protections, transaction limits, and procedures for replacing credentials. Where feasible, maintain more than one suitable payment or funding option, such as another provider or an agreed credit facility. Do not assume a backup will be usable: review its terms, fees, eligibility criteria, notice periods, collateral requirements, and applicable legal or regulatory obligations. Ensure authorized decision-makers can securely access accounts and payment tools during staff absences, using strong authentication and tested recovery steps. Periodically test contingency arrangements with relevant staff and update written instructions when providers, roles, or systems change.

    Resilience improves when essential work does not depend on one supplier, employee, system, communication channel, or business relationship. Start by documenting critical processes, including who performs each task, what information and tools are required, and which decisions must be made under pressure. Keep instructions current and accessible to authorized staff so operations can continue when a key person is unavailable. Cross-train employees on priority responsibilities, and assign backups for roles that require specialized knowledge. This reduces single points of failure while helping teams respond more confidently to unexpected absences or service interruptions.

    Map suppliers and service providers that support essential operations, then identify credible substitutes for each critical dependency. Consider lead times, geographic concentration, contractual obligations, and whether alternatives can meet security and quality requirements. Maintain secure backups of essential records, financial information, contact lists, and operating documents. Use more than one appropriate backup method where practical, and store copies separately from the primary systems they protect. Backups should be encrypted, tested through regular recovery exercises, and limited to authorized users; an untested or broadly accessible copy may not provide reliable protection.

    Prepare alternate ways to communicate with employees, customers, banks, and business partners if normal phone, email, or online services fail. Keep current contact details and agree in advance on fallback channels, verification steps, and who may issue official updates. Protect these channels and contact records from unauthorized access, and share sensitive information only through approved, secure methods. Network resilience includes more than technical infrastructure such as connectivity, devices, data, and payment systems. It also depends on trusted human relationships: suppliers, peers, advisers, customers, and community contacts may provide timely information, practical support, or referrals during disruption. Maintain these connections before a crisis, clarify expectations, and periodically test both technical recovery and communication plans. Together, prepared people, secure information, and workable alternatives make it more likely that essential services can continue or be restored quickly.

    Turn risk findings into a practical continuity plan by converting each significant exposure into decisions and actions. For every scenario, identify the services that must continue, the people responsible for response, and the resources needed to keep operations functioning. Assign a primary lead and backup for each role, including incident coordination, technology recovery, finance, communications, and staff safety. State clearly who may authorize emergency spending, suspend services, contact regulators, or move work to an alternate site when normal approval channels are unavailable.

    Set activation triggers in advance, such as a facility closure, prolonged outage, suspected data compromise, payment failure, or disruption to a critical supplier. Link each trigger to immediate actions rather than broad intentions: account for employees, secure locations and systems, preserve records, notify decision-makers, and assess which essential services remain available. Keep emergency contacts current, including bank relationship managers, payment providers, insurers, key vendors, landlords, and relevant public agencies. Record escalation numbers, account access procedures, after-hours contacts, and the information each party will require.

    Document alternate operating procedures for essential work, including remote access, manual processing, alternate payment methods, backup suppliers, and temporary work locations. Prepare customer and employee communication templates that can be adapted quickly, with approved channels, message owners, and guidance on what is known, what remains uncertain, and when updates will follow. Define a recovery sequence that puts life and physical safety first, then restores essential services, protects sensitive information, and stabilizes cash flow. Specify the conditions for resuming normal operations and the person who confirms each transition.

    Test the plan through periodic tabletop exercises that let staff practice decisions without interrupting daily operations. Add practical checks, such as restoring backup data, contacting critical vendors, or processing a transaction through an alternate payment method. Record gaps, assign owners, and set deadlines for corrective actions; a test is valuable only when its findings lead to changes. Review the plan on a regular schedule and update it after exercises, near misses, major business changes, or shifts in banking, suppliers, technology, or key relationships. Keep the latest version accessible to authorized staff, including when usual systems are unavailable.

  • Grow with Purpose: Building a Business Without Losing Your Well-Being

    Grow with Purpose: Building a Business Without Losing Your Well-Being

    Grow with Purpose: Building a Business Without Losing Your Well-Being

    Growth Takes Persistence

    Scaling a business rarely happens in a straight line. As your company grows, customer expectations shift, new challenges appear, and plans that once worked may need to change. Setbacks are part of the process—not proof that you should give up. Staying focused on the needs of your customers and team can help you make thoughtful decisions and keep moving toward sustainable success.

    Persistence does not mean pushing ahead without a plan. Revisit your goals, listen to feedback, and identify the next practical step. If a strategy is not working, adjust it rather than treating a change of direction as failure. Progress often comes from learning quickly and responding with care.

    Protect the Energy Behind the Work

    Ambition can be motivating, but constant pressure can affect your health, judgment, and relationships. Rest, nourishing meals, movement, and time away from work are not rewards you must earn after reaching a milestone. They support the focus and resilience needed to lead well over time.

    Make well-being part of your working rhythm. Set reasonable boundaries around your hours, take short breaks, and schedule time to recharge. When possible, delegate responsibilities and create processes that do not depend on one person being available every moment. A healthier pace can help you and your business stay capable through demanding periods.

    Build a Mindset That Can Adapt

    A steady mindset is not about pretending every obstacle is easy. It means recognizing what is difficult, separating what you can control from what you cannot, and choosing a constructive response. Celebrate meaningful progress, even when it is incremental, and treat mistakes as information you can use.

    Growth is most valuable when it meets real business needs without sacrificing the people doing the work. Keep your purpose in view, stay open to change, and seek support when you need it. You do not have to choose between striving for success and caring for your well-being. With patience, clear priorities, and sustainable habits, you can make room for both.

  • Building Generational Wealth Through Strategic Business Investment

    Building Generational Wealth Through Strategic Business Investment

    Building Generational Wealth Through Strategic Business Investment

    The Long-Term Purpose of Business Investment

    Investing for the future is not simply about achieving short-term financial growth. It is a disciplined approach to creating assets, strengthening financial security, and providing opportunities for future generations. In a business finance context, this means directing capital toward ventures, resources, and strategies that can produce sustainable value over many years.

    Successful investors understand that wealth accumulation requires patience. Businesses may experience changing markets, rising costs, and periods of uncertainty, but a well-planned investment strategy can help manage these challenges. The objective is to build a resilient financial foundation rather than pursue temporary gains.

    Creating Value Through Strategic Decisions

    Generational wealth gathering begins with informed decision-making. Business owners and investors should assess potential returns, operating risks, market demand, and the strength of management before committing funds. Diversifying investments across industries, assets, or business activities can also reduce dependence on a single source of income.

    Reinvesting profits is another important principle. Rather than distributing every gain, a company may use part of its earnings to improve technology, develop employees, expand operations, or enter new markets. These decisions can increase productivity and strengthen the enterprise’s value over time.

    Protecting Wealth for Future Generations

    Building wealth is only one part of the process. Preserving it requires clear financial controls, responsible borrowing, tax planning, and appropriate legal structures. Families and business partners should establish succession plans that explain how ownership, leadership, and assets will be transferred.

    Financial education is equally important. Future beneficiaries who understand budgeting, investment risk, and business responsibilities are better prepared to manage inherited assets. Open communication can help align expectations and reduce conflict when important financial decisions arise.

    A Sustainable Vision for Prosperity

    Investing for future prosperity requires consistency, flexibility, and a willingness to learn. Economic conditions will change, but careful planning can help businesses adapt while protecting their core objectives. By combining strategic investment with sound governance and intergenerational education, families can transform current resources into lasting financial opportunity.

  • Making AI Work for Small Businesses: A Practical Path from First Experiment to Everyday Advantage

    Making AI Work for Small Businesses: A Practical Path from First Experiment to Everyday Advantage

    Making AI Work for Small Businesses: A Practical Path from First Experiment to Everyday Advantage

    Effective AI adoption begins with a business problem, not a technology purchase. Before comparing platforms or subscribing to a new tool, identify where work is consuming unnecessary time, creating avoidable errors, or limiting growth. This approach keeps investment connected to a practical outcome and helps a small business test AI without disrupting essential operations.

    Review everyday activities across the organization. Useful opportunities may include answering recurring customer questions, scheduling appointments, processing or locating documents, monitoring inventory, supporting bookkeeping, following up with sales leads, or producing routine marketing content. Look for tasks that are repetitive, time-consuming, data-heavy, or governed by clear rules. These characteristics often indicate that AI can provide assistance through drafting, classification, summarization, prediction, or workflow automation.

    Rank potential applications using consistent criteria. Consider the hours that could be saved, the likely financial value, the ease of implementation, the availability and quality of relevant data, and the risks associated with mistakes or inappropriate outputs. A task that promises substantial savings but involves sensitive information or complex judgments may be less suitable as a first project than a modest, low-risk improvement.

    It is also important to distinguish assistance from accountability. AI can suggest a response, summarize a document, flag unusual inventory movement, or prioritize leads. A person should generally remain responsible for decisions involving legal obligations, financial commitments, hiring, safety, customer disputes, or sensitive personal information. Human review should be designed into the process rather than added after a failure.

    Choose one high-value, low-risk pilot with a clearly defined scope. Automating answers to frequently asked questions, provided they are reviewed and limited to reliable information, or summarizing internal documents can offer a manageable starting point. Establish a baseline before implementation: record current response times, weekly labor hours, error frequency, processing costs, or conversion rates. After the pilot, compare the same measures, gather staff and customer feedback, and assess whether the improvement justifies expansion. Measurable evidence creates a sound basis for the next AI investment.

    Small businesses should assess AI tools by practical value rather than impressive marketing claims. The most useful option is not necessarily the one with the largest feature list; it is the one that solves a recurring problem with minimal disruption. Compare usefulness, ease of use, compatibility with existing software, pricing, security controls, scalability, and the quality of vendor support. Check whether the provider publishes clear data-handling policies, offers dependable customer service, and allows users to export their information if circumstances change.

    Different categories serve different needs. General-purpose AI assistants can help with drafting, summarizing, and research, while specialized applications may support recruiting, legal review, or inventory management. Automation platforms connect systems and trigger actions, customer-service tools help manage inquiries, and analytics systems identify patterns in business data. Many companies already include AI features in accounting, sales, scheduling, and productivity software. Starting with capabilities inside familiar tools can be less expensive and easier than requiring employees to adopt an entirely new system.

    A simple workflow should make responsibilities clear. First, define the input, such as meeting notes, an invoice, or a customer message. Next, specify the AI task: create follow-up tasks, extract key details, or draft a response. Establish a human review step before important information is shared or an action is taken. Then decide where the output will be stored and identify the final action, such as assigning a task, updating a record, or sending an approved reply. For example, AI may draft a customer response without sending it automatically, or extract invoice totals for an employee to verify.

    Begin with a limited pilot budget and test free trials carefully. Review subscription limits, per-user charges, usage caps, data-export options, vendor reliability, and cancellation terms. Measure time saved, error rates, employee adoption, and customer impact before expanding. Avoid tool sprawl: too many overlapping subscriptions can increase costs, fragment information, and create maintenance work. A small set of well-integrated tools will usually produce more dependable results than a collection of disconnected experiments.

    Using artificial intelligence in a small business creates responsibilities that extend beyond choosing an effective tool. Owners should understand what information an application collects, whether submitted content is used to train its models, how long data is retained, where it is stored, and which employees, vendors, or other parties can access it. They should also check whether the provider’s practices align with customer contracts, industry rules, privacy requirements, and other legal obligations that apply to the business.

    Employees should not casually enter payment-card details, passwords, confidential contracts, health information, government-issued identifiers, customer records, or proprietary business information into a public AI service. A practical policy can define approved tools and permitted uses, require data minimization, and provide examples of information that must remain outside external systems. Access controls, strong authentication, regular password reviews, and prompt removal of former employees’ permissions reduce avoidable exposure. Staff training should explain both the policy and the reasons behind it.

    Security is only one part of responsible use. AI can produce inaccurate facts, flawed calculations, biased recommendations, incomplete analysis, or misleading customer communications. Human reviewers should verify important outputs against reliable sources and confirm that calculations, claims, and promised terms are correct before anything is published or acted upon. Businesses should retain a simple record of who reviewed significant outputs, what was checked, and how corrections are handled when an error is discovered.

    Some decisions should never be delegated without meaningful human oversight. This includes hiring, lending or credit decisions, pricing that materially affects customers, safety procedures, legal matters, and sensitive complaints or disputes. A person should be able to investigate context, recognize unfair outcomes, explain the decision, and override the system. When AI substantially shapes a customer’s experience, businesses should provide clear, appropriate disclosure and a route to human assistance. These safeguards preserve trust while allowing automation to support, rather than replace, accountable judgment.

    An initial AI experiment becomes a business capability only when its results are measured, documented, and repeatable. Start by comparing performance with the original baseline rather than relying on enthusiasm or isolated examples. Suitable measures may include hours saved, lower operating costs, faster response times, fewer errors, improved customer satisfaction, higher lead conversion, increased output, and a more manageable employee workload. The right metric depends on the workflow: a support team may track response time and satisfaction, while a finance process may prioritize accuracy and correction costs.

    Numbers should be combined with feedback from the people who use the workflow every day. They can identify confusing outputs, hidden manual steps, privacy concerns, and situations in which the tool creates more work than it removes. Review results after a defined trial period, then decide whether to refine the process, replace the tool, pause its use, or discontinue it. Calculate total cost, including subscriptions, integration, training, supervision, maintenance, and the time employees spend checking or correcting results.

    Training should be short, practical, and specific to each role. It should explain approved tools, effective prompting, fact-checking expectations, privacy rules, escalation procedures, and clear examples of acceptable and unacceptable use. Employees need to know when human review is mandatory and whom to contact when an output is uncertain. Reusable prompts, templates, checklists, and standard operating procedures can make quality less dependent on one experienced employee and help new staff adopt the workflow consistently.

    Growth is safest in phases. First stabilize one successful workflow and establish ownership, documentation, and regular review. Next connect it to adjacent processes only when the original results remain reliable. Reassess security, accuracy, cost, and customer impact as usage expands. AI can support routine decisions and increase capacity, but human expertise should remain the foundation for customer relationships, sensitive judgments, and strategic choices.

  • Why Small Wins Matter on the Road to Growth

    Why Small Wins Matter on the Road to Growth

    Progress Begins with Small Steps

    When you are a beginner, progress can feel slow. You may compare yourself with people who have more experience and wonder whether your efforts are making a difference. In these moments, celebrating small wins can help you recognize how far you have already come. Completing a first task, understanding a difficult idea, or practicing consistently are all meaningful signs of growth.

    Small Wins Build Confidence

    Every achievement, no matter how minor it seems, provides evidence that you are capable of learning and improving. This evidence strengthens confidence over time. Instead of waiting for a major result before feeling successful, take a moment to acknowledge each step forward. Confidence built through regular effort is more dependable than motivation based only on large accomplishments.

    Recognition Encourages Consistency

    Beginners often lose momentum because they focus only on what remains unfinished. Recognizing progress changes that perspective. A simple habit, such as writing down three things you accomplished each week, can make improvement easier to see. This positive reflection encourages you to continue practicing, even when progress is not immediately obvious.

    Growth Is More Than a Final Result

    Success is not created by one dramatic breakthrough. It usually develops through repeated effort, useful mistakes, and gradual improvement. Small wins matter because they show that the process is working. They also help you set realistic goals, adjust your approach, and appreciate the skills you are developing along the way.

    Celebrate Without Losing Focus

    Celebrating progress does not mean ignoring areas that need work. It means balancing ambition with self-recognition. Notice what went well, identify the lesson, and then choose the next manageable challenge. As a beginner, this approach can make growth feel more rewarding and success more sustainable.

  • Strategies for Leveraging an Audience to Scale Your Business

    Strategies for Leveraging an Audience to Scale Your Business

    Understanding Your Audience

    To effectively leverage your audience for scaling, it’s crucial to have a thorough understanding of who they are. Conduct surveys or utilize analytics tools to grasp their preferences, needs, and behaviors. Knowing your audience helps you create content and offers that resonate deeply, fostering loyalty and engagement.

    Creating Valuable Content

    One way to capitalize on your audience is by providing valuable and relevant content. This not only attracts new followers but keeps your current audience engaged. Whether it’s through blog posts, videos, or podcasts, focus on delivering insights that help your audience solve their problems. When they find value in your content, they’re more likely to share it with others, amplifying your reach.

    Utilizing Feedback for Continuous Improvement

    As you scale, don’t forget to solicit feedback from your audience. This is essential for adapting your strategies to better serve their needs. Regularly ask for their opinions on services, products, or content. This two-way communication helps improve your offerings while ensuring your audience feels valued. By continuously refining your approach based on their input, you not only scale effectively but also enhance customer satisfaction.

  • Effective Strategies for Building Wealth Through Finance Management

    Effective Strategies for Building Wealth Through Finance Management

    Effective Strategies for Building Wealth Through Finance Management

    Understanding Finance Management

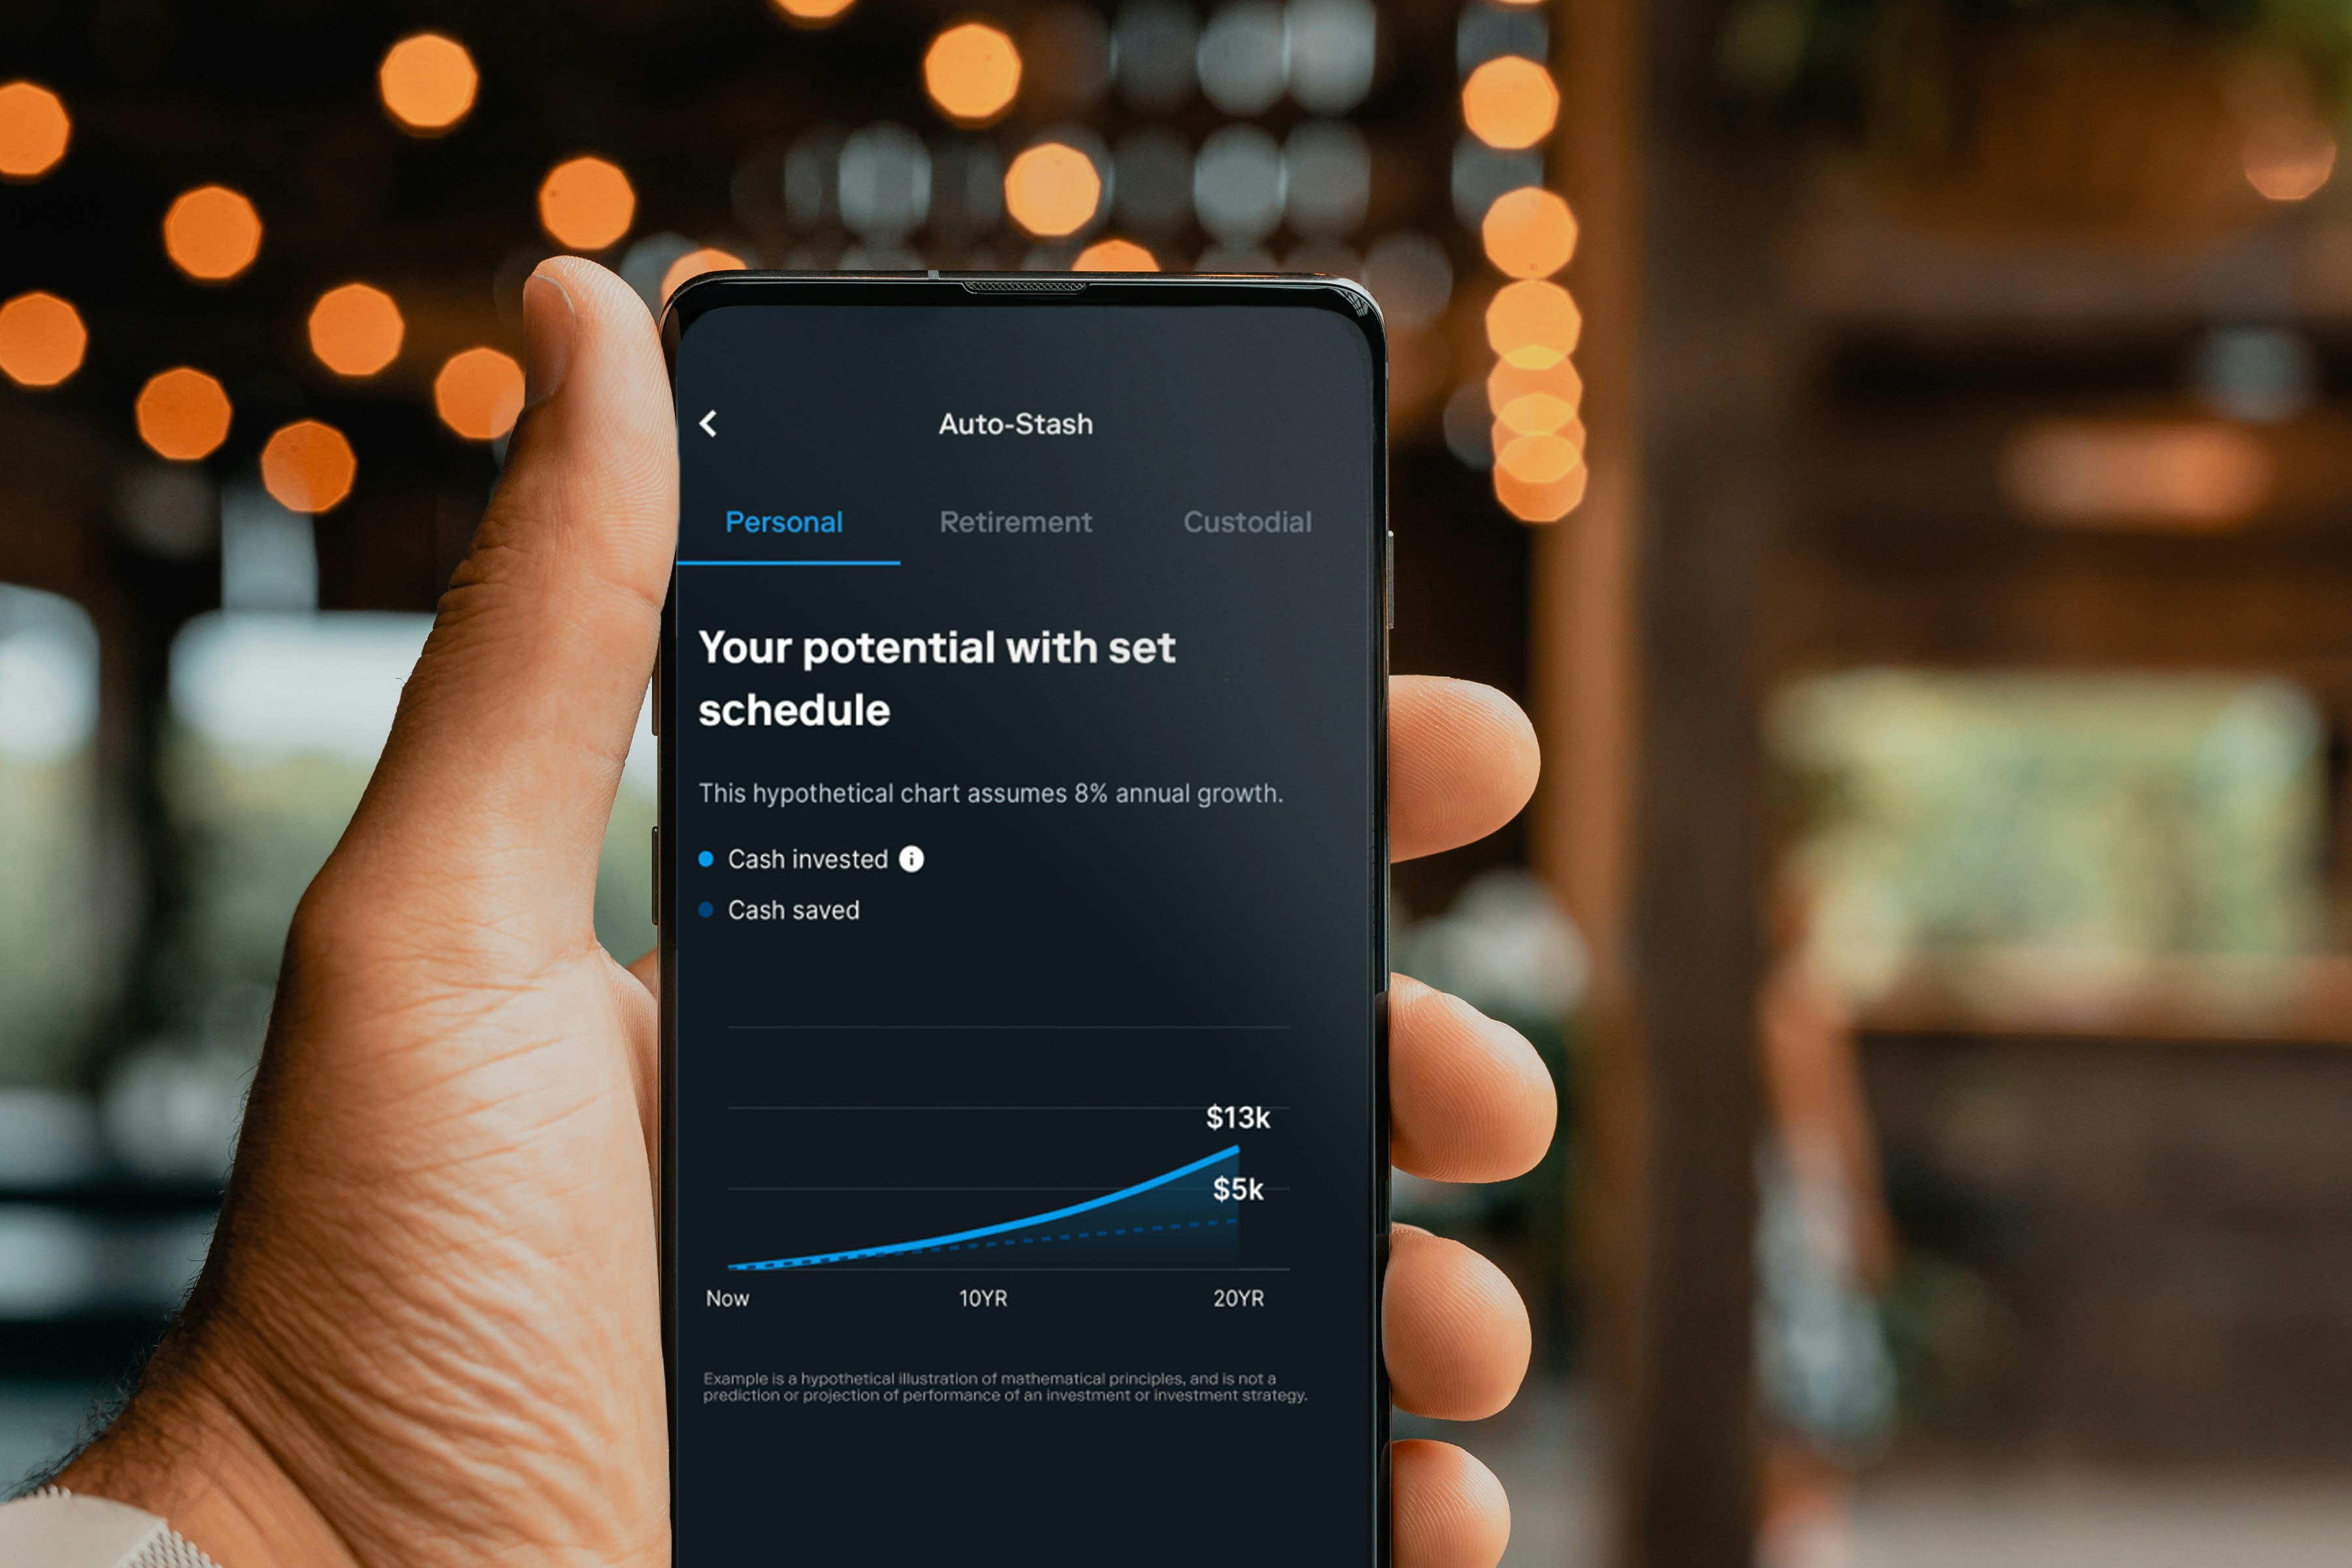
    Managing your finances is a crucial step toward building wealth. It involves planning, organizing, directing, and controlling your financial activities. This holistic approach enables you to make informed decisions about investments, savings, and expenditures. Awareness of your income and expenses is the first step in creating a roadmap for financial stability and growth.

    Wealth Building Strategies

    There are various strategies for building wealth, and one effective method is investing in real estate. Real estate can generate passive income through rental properties or appreciation over time. Additionally, incorporating technology and artificial intelligence into your investment strategy can optimize your decision-making process, providing you with data-driven insights that enhance your investment portfolio.

    Tips for Getting Started

    To get started on your wealth-building journey, begin by setting clear financial goals. Outline your short-term and long-term objectives, whether it’s saving for retirement, buying your first home, or funding education. Additionally, educate yourself on market trends and investment opportunities. Utilize resources such as books or online courses to build your financial literacy, and consider consulting with a financial advisor to tailor a strategy that meets your needs.

  • Elevate Your Business Outlook and Financial Success

    Elevate Your Business Outlook and Financial Success

    Understanding the Importance of a Positive Business Outlook

    Improving your business outlook is essential for sustainable growth and success. A positive mindset can lead not only to better decision-making but also to increased employee morale and productivity. By fostering an optimistic view within your organization, you open the door to new opportunities and collaborations that can greatly benefit your venture.

    Strategies to Enhance Your Financial Management

    Finance is the backbone of any successful business. To enhance your financial health, start by evaluating your current financial strategies. It’s crucial to maintain a balanced budget, keep detailed records of your expenditures, and regularly review your income streams. Exploring new avenues for revenue, such as diversifying your product offerings or tapping into new markets, can also improve your overall financial outlook.

    Embracing Change for Future Growth

    Adapting to changes in the market is vital. Stay informed about industry trends and technological advancements that could impact your business. By being proactive and willing to pivot when necessary, you can ensure that your business remains competitive and relevant. Remember, a business that embraces change will not only survive but also thrive in challenging times.